
The Value of Outsourcing Financing: Why Capital Markets Strategy Is More than an Operational Decision

The Value of Outsourcing Financing: Why Capital Markets Strategy Is More than an Operational Decision
Private equity’s realization problem is evident and unquestioned. Exit timelines have stretched across the industry, hold periods have extended well beyond historical norms, and the continuation vehicle has gone from an exception to a standard feature of the GP toolkit. For many middle-market sponsors, the ability to monetize individual portfolio assets is constrained in ways that were difficult to anticipate even a few years ago.
Against that backdrop, a quieter but increasingly significant trend has taken hold: GPs are finding a different kind of exit. Rather than waiting on their portfolio companies, a growing number of private equity managers are monetizing the GP itself. GP stake transactions, in which a larger manager, institutional investor, or dedicated GP-stakes vehicle acquires a minority interest in a private equity firm, have accelerated meaningfully.
According to PitchBook’s Q4 2025 US Public PE and GP Deal Roundup, 2025 saw 24 GP stake transactions totaling $3.5 billion in deal value, the highest annual total since 2021 and nearly five times the 2023 figure. Strategic acquisitions and minority-stake transactions are signaling continued consolidation and investor demand for diversified revenue streams.
For GP principals who have spent years building a firm, the implications are significant. The value a counterparty will pay for a stake in the GP is, at its core, a multiple of Fee-Related Earnings (FRE) — the stable, recurring management fee income that remains after operating expenses. Mega-cap publicly traded alternative managers currently trade at roughly 16x distributable earnings (which includes less predictable revenue streams such as carried interest), while private GP stakes transactions in seasoned, proven managers have been observed at or above 20x FRE given the higher quality and predictability of that income stream.
That multiple turns every dollar of unnecessary overhead into a meaningful lost enterprise value. And for most middle-market GPs, no overhead line is more misunderstood in this context than capital markets.
“At 20x FRE, a $2.5 million capital markets overhead line doesn’t show up as an expense. It shows up as $50 million in GP enterprise value that doesn’t exist.”
GP Monetization Trend Is Real and Growing
The mechanics of a GP stake transaction are straightforward. A sophisticated buyer, such as a dedicated GP-stakes vehicle, a larger alternative asset manager, or a strategic institutional investor, acquires a minority position in the management company. Principals take some chips off the table, and the buyer receives a passive economic interest in ongoing fee income. In short, neither party controls the other.
However, what was once primarily a tool for the largest platforms has moved firmly into the middle market. Recent transactions illustrate the breadth of activity.
- Blue Owl Capital took a minority stake in Veritas Capital, a technology-focused buyout firm with $50 billion in AUM.
- Bonaccord Capital Partners acquired a minority stake in Kingswood Capital Management, a Los Angeles-based middle-market buyout manager with approximately $3 billion in AUM.
- Wafra, which manages $192 billion in AUM across PE, real assets, and private credit, acquired a minority stake in Ardian.
- Atlas Holdings, a middle-market industrial buyout firm, received a strategic minority investment from both Blackstone and Blue Owl, which is a notable example of two of the world’s largest alternative managers simultaneously backing the same GP.
PitchBook data confirms the trend is accelerating. Across all GP-related M&A activity — including strategic acquisitions, mergers, and minority investments — 2025 deal value reached $25.1 billion, the second-highest annual total on record. The report notes that “a significant portion of the activity throughout the year was driven by the growing GP stakes activity seen in middle-market managers.”
The exit environment for individual portfolio assets has further reinforced this dynamic. With hold periods extending and continuation vehicles becoming standard, GP-level monetization has emerged as a complementary liquidity strategy that does not depend on the underlying portfolio exit cycle.
Valuation Math: FRE Is the Asset
Understanding why capital markets strategy matters to GP valuation requires a brief tour of the mechanics of pricing GP stakes. When a counterparty underwrites a minority stake in a management company, they are primarily buying a share of the most valued income stream: Fee-Related Earnings or the stable, largely fixed revenue stream generated by management fees, net of the overhead.
As a reference point, the seven major publicly traded alternative managers currently trade at a median of approximately 16x Price/DE on 2025 actuals, and that figure reflects distributable earnings, which includes carried interest and other less predictable revenue. Private GP stakes for seasoned managers with clean, recurring fee income have historically traded at or above 20x FRE, given the premium placed on earnings quality.
The implication is direct. Overhead that reduces FRE reduces GP enterprise value at that same multiple. For example, $2.5 million spent on capital markets overhead, or two to three dedicated professionals, represents approximately $50 million in foregone GP enterprise value. For most middle-market GPs, it is a number larger than the carried interest they expect to realize in any given year.
Capital Markets Approach: FRE Impact and GP Enterprise Value at Risk
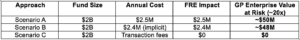
Note: Based on a representative $2B AUM fund. FRE multiple of ~20x reflects observed GP stake transaction pricing for seasoned middle-market managers; publicly traded mega-cap alternative managers trade at ~16x distributable earnings per PitchBook Q4 2025 data. Implicit cost under Option B reflects estimated deal team time allocation; see Section 3 for full methodology.
Comparing Alternative Approaches to Capital Markets
The capital markets decision looks different depending on fund size. Larger managers, such as those with AUM above $2 billion, are more likely to maintain a dedicated in-house function at a sufficient scale that makes economic sense. But for a significant swath of the middle market, the choice between three approaches carries valuation consequences that are rarely modeled explicitly.
Scenario A: Dedicated, In-House Capital Markets Team
A firm hires dedicated professionals, such as a managing director with a credit background and/or lender relationships and, depending on volume, a mid-level support hire. This creates a specialized function with clear accountability and a focused mandate.
The cost is visible and direct. A fully burdened MD-level hire typically runs $1.5 million or more in all-in annual compensation. Add a mid-level hire at approximately $1 million, and the two-person team for a $2 billion fund costs approximately $2.5 million per year. That number sits on the FRE bridge. At 20x, it represents $50 million in GP enterprise value absorbed by unnecessary overhead.
Scenario B: Deal Team Manages All Financing Activities
A more common approach in the middle market is for financing activity to be absorbed by existing deal team professionals, alongside their primary investment responsibilities. The cost has no direct line item, but the implied impact is very real.
Consider a $2 billion fund with four deal-team silos, each staffed with professionals at multiple levels. A reasonable estimate is that mid-level professionals (from associate to principal) spend approximately 15% of their time on financing-related activities over the course of a year, including lender outreach, process management, documentation, and relationship maintenance. At a blended all-in cost of roughly $4 million for a representative four-person deal team, 15% time allocation translates to an implicit annual FRE cost of approximately $2.4 million across four deal team silos.
That figure is comparable to Option A’s FRE impact, but without the visibility, specialization, or institutional lender coverage that a dedicated hire would nominally provide. The cost is absorbed rather than explicit, which is precisely why it persists. Furthermore, there is opportunity cost associated with the investment team dedicated 15% of time to financing, rather than focusing time and effort on value creation plan, finding the next deal, etc.
Scenario C: Outsourced Capital Markets
The outsourced model differs from Options A and B in one structurally important respect: the cost does not flow through the GP. Rather, transaction fees and financing-related expenses are borne by the deal and not the management company. FRE is cleaner and higher. At 20x FRE, the difference in GP enterprise value is not a soft benefit or a “pie in the sky” projection. It is the simple arithmetic of how GP stakes are priced, applied to a structural choice that can be made today.
The Question Worth Asking
Most middle-market GPs have never modeled what their capital markets function costs at the FRE level. The expenses are either visible as headcount or absorbed invisibly as deal team time. Neither typically surfaces in a discussion about GP enterprise value.
That will change. The data is clear about GP stake transactions accelerating, with sophisticated, deep-pocketed investors eager to find more deals and strong management companies. They will look carefully at overhead structure, at FRE margins, and at whether the cost base reflects a management company built for scale or one that grew organically without the benefit of deliberate design.
The firms that have already made this structural adjustment, converting a fixed, FRE-dilutive overhead line into a variable, deal-level cost, will command better multiples and have greater flexibility in how they approach GP-level liquidity.
The question worth asking is not “Can we afford to outsource capital markets?” At 20x FRE, the more honest question is: “Can we afford not to?”
Sources
PitchBook. Q4 2025 US Public PE and GP Deal Roundup. February 27, 2026. Data on GP stake transactions, deal activity, and public alternative manager comparables.
Blue Owl Capital / Blackstone. “Blackstone and Blue Owl Announce Strategic Minority Investment in Atlas Holdings.” blueowl.com, 2025.
GLAS Funds. “Understanding General Partner (GP) Stakes Investing.” glasfunds.com/perspectives. Referenced for GP stakes transaction mechanics and FRE multiple context.
Configure Capital internal analysis. Compensation and time-allocation estimates reflect market-rate benchmarks for middle-market private equity professionals.
 About Ravi Mehta
Ravi brings over 12 years of investment banking, private equity, and credit expertise to the middle market, having raised more than $5 billion in GP-led secondaries capital for his clients.
Prior to joining Configure, Ravi was a key member of PJT Partners’ Private Capital Solutions Group, where he led origination, execution, and distribution of complex secondaries transactions. Before PJT, he served as an investor at The Stephens Group — a family office managing over $2 billion in private equity assets — where he evaluated new investment opportunities and oversaw portfolio companies. Earlier in his career, Ravi advised financial institutions on M&A transactions at Wells Fargo Securities and covered middle-market credit positions at PNC Financial Services.
Ravi holds a B.B.A. with majors in Accounting and Finance from the University of Georgia (Go Dawgs!) and is a FINRA Registered Representative (Series 7, 63, and 79).
In his spare time, Ravi enjoys catching comedy shows in the West Village and hiking and biking near his home in Long Island, where he resides with his wife.
 About James Bardenwerper
James joined Configure Partners in 2018 as an Associate and was promoted to Director in 2024. Before joining Configure Partners, he was at Genuine Parts Company, supporting merger and acquisition efforts and strategic planning. He began his career as an Analyst at SunTrust Robinson Humphrey, where he spent three years advising clients on debt and equity capital raises across various industries.
James received a bachelor’s in Finance from the University of Kentucky. He is a FINRA General Securities Registered Representative (Series 79, 63).